What Alliance Bank Is Actually Doing With AI — And How Your Business Can Copy It
A Malaysian bank put retail loans on one path with CTOS and JurisTech. The useful part is a file a smaller business can copy without a core lending system.
ButterflyCopilot
0105
What they achieved
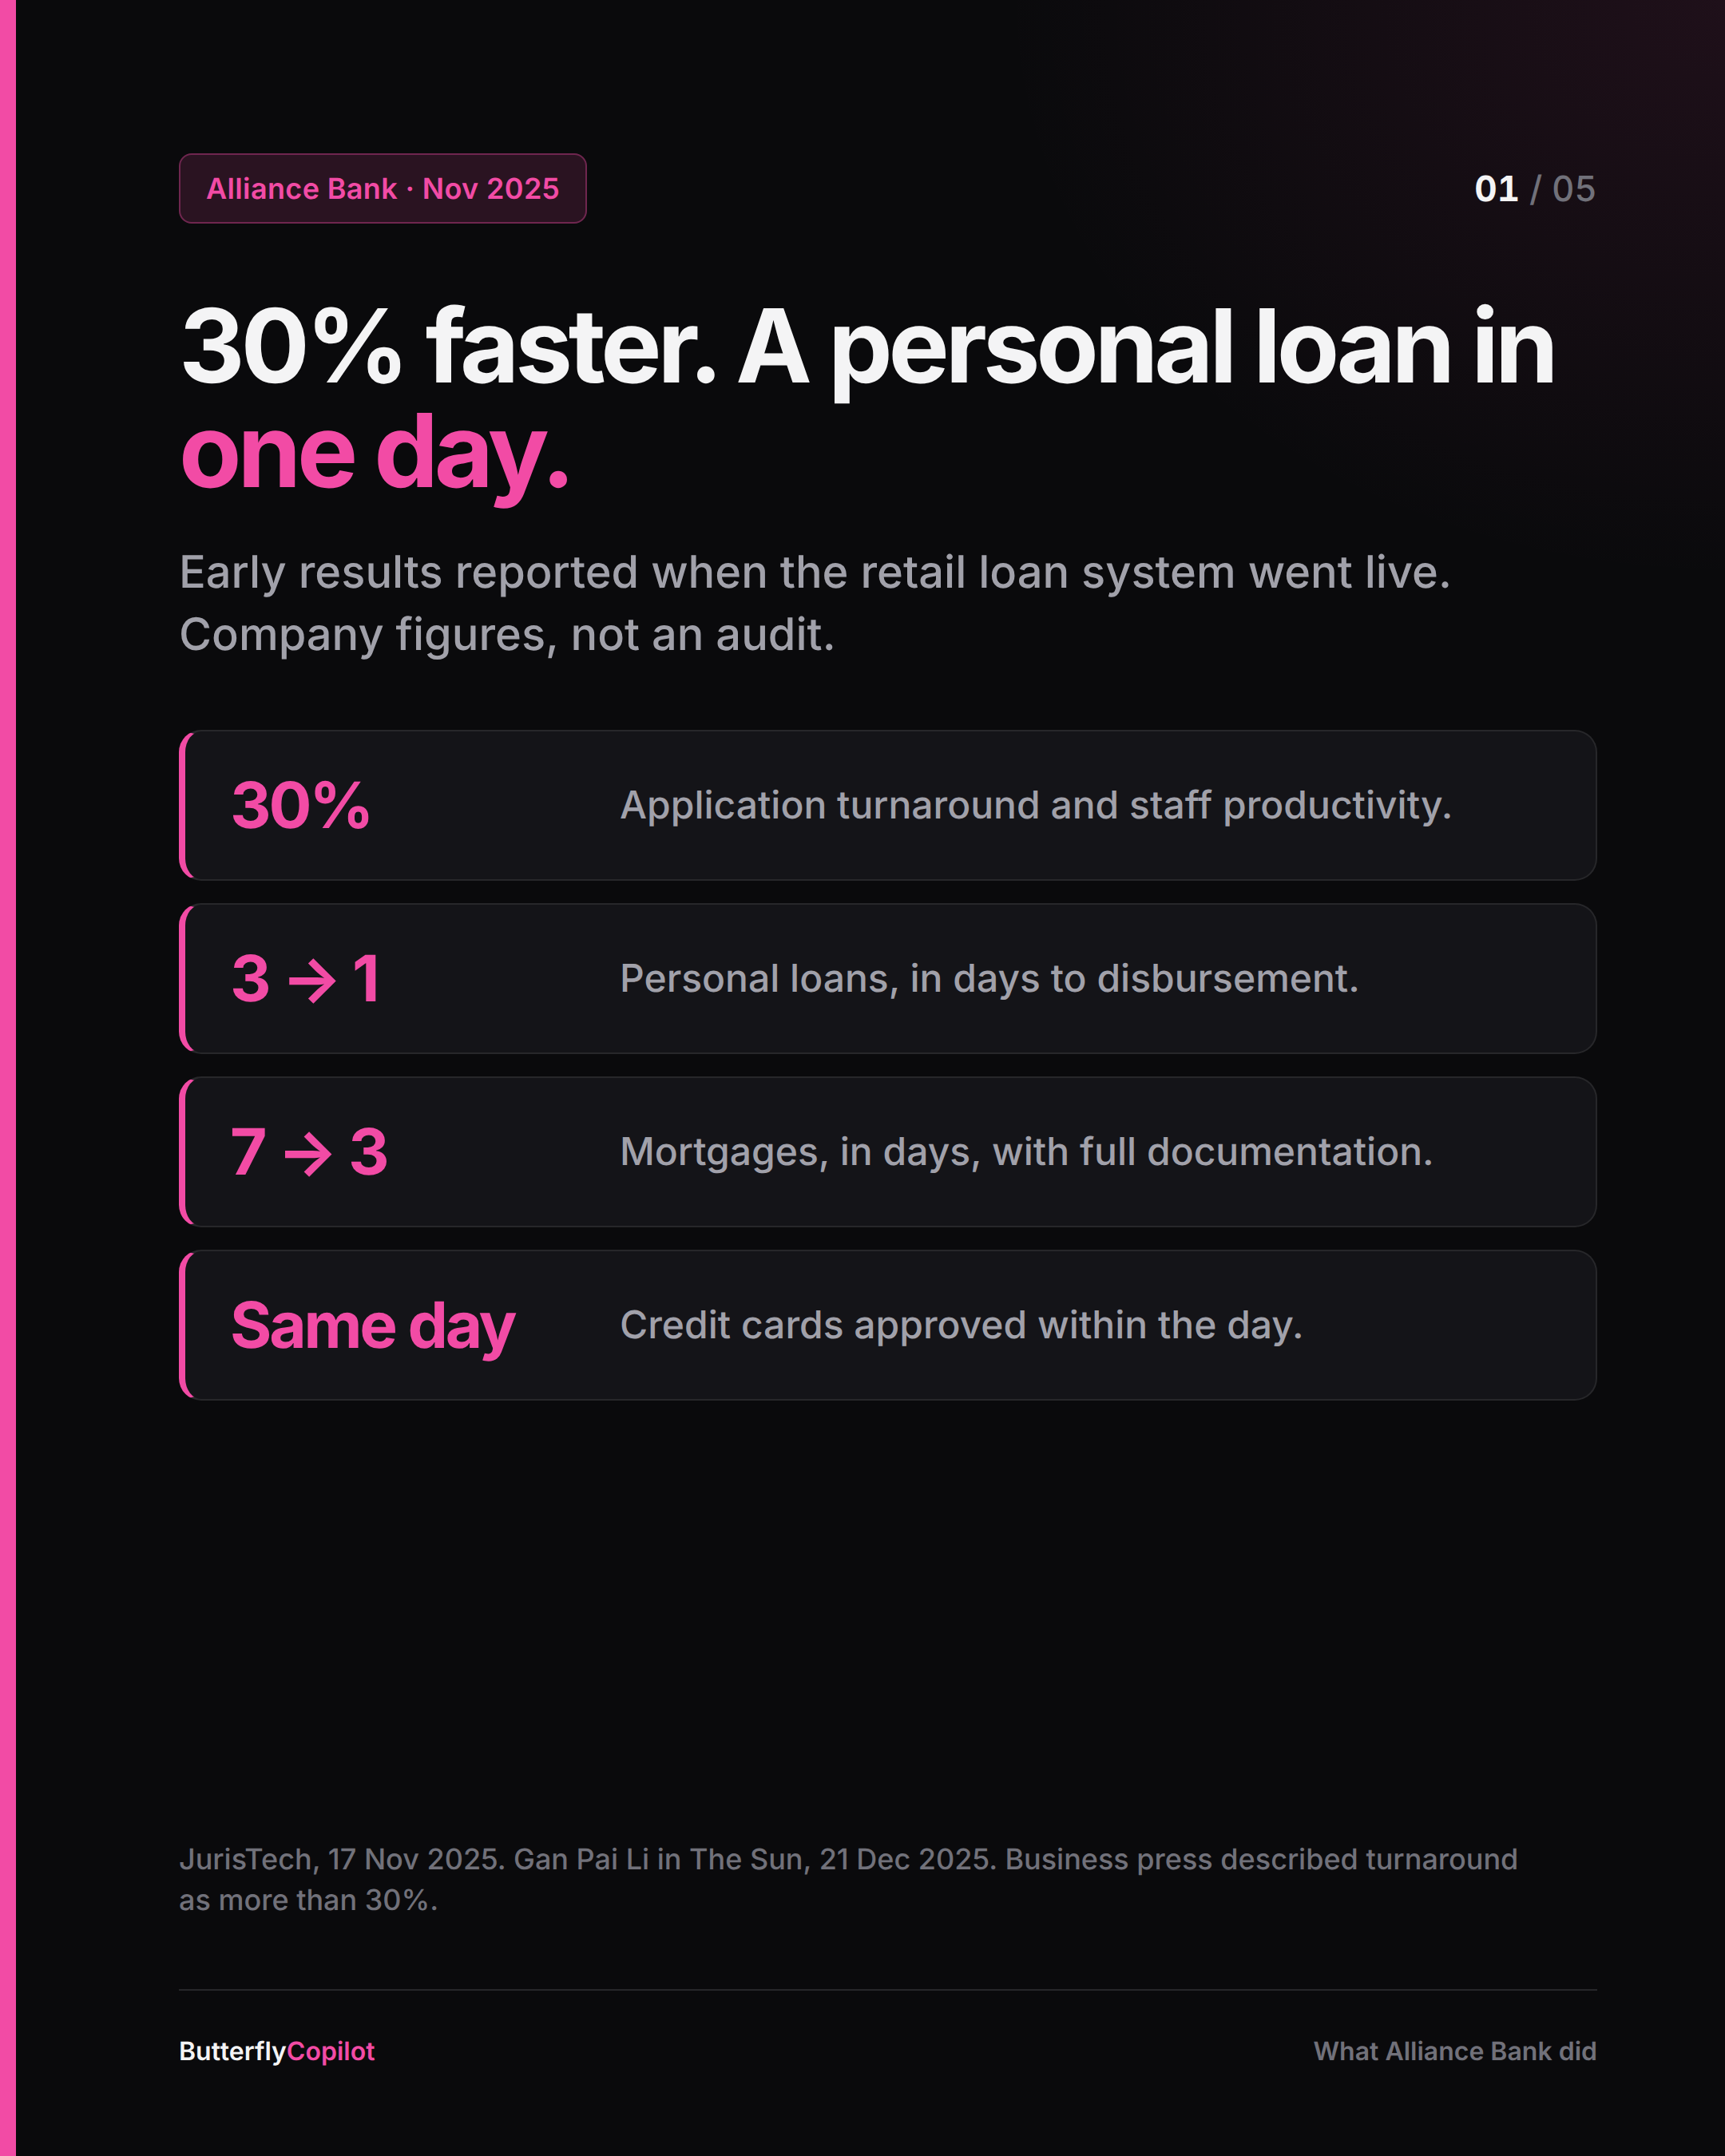
Alliance Bank Malaysia has published early numbers from a new retail loan system.
Application turnaround and staff productivity improved by 30%. Personal loans that took three days are disbursed within one day. Mortgages moved from seven days to three. Credit cards are approved within the day.
Those figures come from the people who built and run it. JurisTech’s 17 November 2025 release states the 30% and the three clocks. Gan Pai Li, Alliance Bank’s Group Chief Consumer Banking Officer, later told The Sun the same day counts, including that the mortgage timing was with full documentation, and that the bank had seen a productivity uplift across all three products. BusinessToday and Fintech News, covering the launch, described the turnaround gain as more than 30%, and personal-loan disbursement as same-day.
Treat that as one launch, reported by the bank and its partners. It is not an independent audit. The shape of the result is still the useful part: fewer days in a file that used to wait on people.
The system was awarded in May 2023. The first production release went live within 12 months. They did not switch every product on the same morning.
What they do
Alliance Bank is a retail bank. This project is the path a customer walks from “I want this product” to “the money is out, and someone is looking after the account.”
The platform is a Retail Loan Origination System, built with two Malaysian partners:
- CTOS Data Systems, for credit data
- JurisTech, for the lending workflow
The path they put on it is the whole origination file, not a chatbot beside the old process:
Lead and digital onboarding
        ↓
Documents
        ↓
Origination and decisioning
        ↓
Disbursement
        ↓
Credit administration
Three products are already on that path: mortgages, personal loans, and credit cards.
Share margin financing is next. It is not live.
Gan described the rollout in The Sun as phased. Product after product. In the six months before that December 2025 interview, the uplift she talked about was across the three products already on the system.
That is the business they are in. Move a complete file through a decision, faster, without losing the ability to see who touched it.
How they do it
They did not start by asking one model to run the bank.
The public account is more specific than that, and more useful.
A different clock for each product
See Wai Hun, JurisTech’s CEO, said the platform runs from digital onboarding and prescreening through loan documentation and disbursement. It is configurable, so a workflow can be tailored to a customer segment. She described that as a fit for Alliance Bank’s progressive approach.
Gan’s version of the same idea is plainer. They did it in phases. A mortgage with a full document pack is not a personal loan. Seven days to three is a different job from three days to one.
Credit data in the decision, not only the form
CTOS sits in the decision. Loh Kok Leong of CTOS told The Sun the bank can look at traditional and alternative credit data, and that putting those insights into the decision is how they reduce bias and speed up a consistent answer. The Sun identified him as interim group CEO; JurisTech’s November release called him group chief executive.
A smaller firm should not read that as “sign up for a bank bureau and you are done.” CTOS and CCRIS access for credit decisions is a regulated path. The copyable idea is narrower: the decision should use an agreed source of facts, not only what the applicant typed into WhatsApp.
Deterministic checks, on two jobs
See said the bank has started using deterministic AI for specific tasks: document verification and prescreening. The point of “deterministic” is dull on purpose. The same file should produce the same check. The agent handles repetitive, rule-based work. Human oversight stays.
That is a document clerk with a written standard. It is not a model freelancing a credit opinion.
Straight-through decisioning is what sits on top of those checks. If the file already fits, it can move. JurisTech’s release ties that to the clocks above: personal loans out within a day, cards approved within the day, mortgages from seven days to three.
The generative layer is later
The launch write-ups also describe a next step: a proof of concept for generative AI through Juris AICraft. Some reports shorten that name to JurisAI. The planned work, as JurisTech lists it, is a copilot for document handling and credit-paper drafts, adaptive credit assessment, virtualised decisioning, and more personal journeys.
That is not what produced the 30%.
The live system is the path, the data, and the rule-based checks. The drafting copilot is scheduled after the path exists.
Gan also said the immediate aim was not a monetary saving. The new workflow let the bank see who entered a file, how fast credit underwriters worked, and how productive they were. The scoreboard they talked about in public was days, and whether a person could see the queue.
The hard parts
A 30% headline is easy to screenshot. The public record also shows why this took a year, and why a smaller business should not skip to the last slide.
It was phased, and it still took about a year to first release. Awarded May 2023. First production release inside 12 months. Then more products. Gan’s line, “product after product,” is the implementation plan. A personal loan and a mortgage do not share a checklist or a clock.
Three organisations had to mean the same thing by “done.” The bank owns the customer and the policy. CTOS owns a body of credit data. JurisTech owns the workflow software. Straight-through only works when those three agree which files are allowed to pass.
They did not let a generative model approve credit. The AI described as live is deterministic document verification and prescreening. See’s line in The Sun is that human oversight remains essential. Juris AICraft is a proof of concept on the roadmap, including help drafting credit papers. Copy that order if you copy anything.
The percentage is early and reported, and the write-ups do not match to the decimal. JurisTech says turnaround and staff productivity improved by 30%. BusinessToday says turnaround improved by over 30%, with staff efficiency up. Fintech News says more than 30% on turnaround and staff efficiency. Same launch. No public study with a baseline file you can re-read. Use the numbers as evidence that they measured days and productivity. Do not paste 30% into your own forecast.
New customers are a hope, not a result they have published. Gan talked about the next three to five years: scoring a customer and estimating exposure within minutes, straight-through for most products, and serving people such as gig-economy workers whose income is harder to verify. That is the direction. The launch proved the three products and the clocks above.
Cost was not the scoreboard. If the only number you track is software spend, you will miss the thing this bank actually put in public: how many days a file takes, and whether an underwriter can see the work.
How a smaller business can copy it
You are not going to install Alliance Bank’s loan system. You are also not going to get bank-grade bureau access because an assistant asked for it.
Copy the operating idea.
A file comes in
      ↓
Someone checks it is complete
      ↓
Someone compares it to a written rule
      ↓
Clean files are prepared
      ↓
A person releases anything that commits you
      ↓
You count the days
If the work in your company is “someone keeps chasing documents on WhatsApp, then retypes them into a sheet,” you are in the same shape of problem. Smaller stakes. Same order.
Where this shows up in Malaysia and around the region
- A distributor deciding 30, 60, or 90-day terms for a new dealer
- A clinic, dental practice, or college taking instalments
- A machinery or vehicle dealer packing a financing file for a bank, or for in-house terms
- A property agency checking a tenant file before the landlord decides
- An insurer or takaful agency assembling a proposal pack
Pick one. The bank went product by product. You start with one product.
Step 1 — Name the application
Write one sentence.
New dealer. 30-day trade account. Requested limit in ringgit.
Not “credit for the whole company.” Not “an AI employee.”
If you run two of these, you still start with one. The second gets its own checklist later, the way a mortgage did not borrow the personal-loan clock.
Step 2 — Write the rule you already use
Before any tool. One page is enough.
- Documents you already ask for. SSM profile, MyKad or passport, three months of statements, a quotation, a salary slip, an EPF statement. Whatever your file actually needs.
- The ringgit band that can be prepared without a manager
- The mismatches that always stop the file. Name against SSM. A statement that does not cover the instalment. A company that is not Active.
- The name of the person who is allowed to say yes
If you cannot write the rule, the assistant will invent one. That is the failure this bank avoided by keeping the live checks deterministic.
Step 3 — Split the file into two piles
Complete, inside the limit, no red flag
        ↓
Prepare the pack or the offer
        ↓
A named person releases it

Anything else
        ↓
Stop, with a reason
        ↓
The same person sees it
For this bank, straight-through can end in disbursement. They are a bank, with a policy, a bureau, and a core system.
For you, straight-through ends when the pack is ready. The assistant does not send the money, the contract, or a message that says approved.
Step 4 — Connect the three things you already have
WhatsApp or email
        +
A shared folder
        +
A sheet, or the ledger you already keep
Columns worth having:
- Date received
- Customer
- Product
- Documents still missing
- Inside the rule, or not
- The reason
- Who must decide
- Decision date
- Days in the file
That last column is their turnaround metric, in a form a 20-person firm can actually keep.
Add Xero, a CRM, or SQL when this file needs them. Not on the first afternoon.
Step 5 — Give the assistant one job
Name it.
Application File Agent
It may read the thread, list what is missing, extract the fields on your page, compare them to the written rule, draft the chase message, and fill the tracker row.
It may not invent a figure that is not in the file, approve a limit, send money, or decide that a missing document probably does not matter.
Customer IC images, bank statements, and phone numbers are personal data. Run this in the business workspace. Keep the files in the company folder. Do not paste a MyKad into someone’s personal chatbot account.
Step 6 — Keep a person on the gate
The first month is a ladder, not a launch.
Version 1. The assistant prepares the checklist. A person sends every message.
Version 2. The assistant drafts the chase. A person taps send.
Version 3. The assistant may send a chase only for a missing-document list you have already approved as wording. Anything about money still waits.
Version 4. Clean files inside a small ringgit band are prepared on their own. A person still releases them.
Gan described a phased rollout. See described human oversight as still essential. That is the same ladder, at bank scale.
Step 7 — Count days, not “we have AI”
Before you start, take ten recent files and write down:
- days from first message to decision
- minutes someone spent chasing and retyping
- how many files bounced for a missing document
After thirty files:
- days on clean files
- days on exceptions
- minutes the person still spends
- how often they agreed with the status the assistant gave
The bank’s public scoreboard was turnaround and productivity. It was not a count of models.
Step 8 — Add the drafting copilot second
When the checklist is boringly right, add the thing Alliance Bank scheduled as a proof of concept.
A second pass that writes the internal note, the offer email, or the proposal summary from the checklist you already trust.
It does not change the decision. Juris AICraft’s place in their story is after the path works.
The same pattern, smaller
ALLIANCE BANK

Application
      ↓
CTOS data + documents
      ↓
Deterministic checks
      ↓
Straight through if the file fits
      ↓
A person on the rest
      ↓
Disbursement
A SMALLER BUSINESS

WhatsApp application
      ↓
Your checklist + your ringgit limit
      ↓
The assistant reads and compares
      ↓
A clean file is prepared
      ↓
A person releases
      ↓
You count the days
The infrastructure is different. The order is the same.
The instruction file
Here’s the MD file with instructions for your AI / email assistant.
It is the job brief: the role, the checklist, the rules it must not break, and the note it should hand back to a person. Paste it into the assistant your team already uses. Replace every line marked REPLACE. Delete the sample ringgit figures before a real customer file goes near it.
Download the application-to-yes instructions (.md)Sources
Figures in this article are public statements from Alliance Bank’s partners and from interviews at the launch. They are not an independent audit.
- JurisTech, “Alliance Bank Goes Live with AI-Enabled Loan Origination System from CTOS and JurisTech,” 17–18 November 2025. Award date, 12-month first release, 30% turnaround and productivity, the day counts, the three live products, share margin financing, and the Juris AICraft proof of concept. juristech.net
- The Sun, “Alliance Bank rolls out AI-powered platform to enhance retail loan operations,” 21 December 2025. Gan Pai Li on the phased rollout, the day counts with full documentation, productivity, and the workflow’s visibility. Loh Kok Leong on traditional and alternative credit data. See Wai Hun on deterministic AI for document verification and prescreening, and on human oversight. thesun.my
- BusinessToday, “Alliance Bank Unveils AI-Powered Retail Loan Origination System,” 21 November 2025. Reports turnaround improving by over 30%, staff efficiency up, and same-day personal-loan disbursement. businesstoday.com.my
- Fintech News Malaysia, “Alliance Bank Goes Live with AI-Powered Loan System from CTOS and JurisTech,” 18 November 2025. Reports more than a 30% improvement in turnaround and staff efficiency, and same-day disbursement for personal financing. fintechnews.my